
There is still a fair amount of hesitation around airline miles in India.
People often ask whether Air India Maharaja Points are actually worth collecting, whether transferring credit card points makes sense, or whether it is simply easier to stick with cashback.
The answer depends entirely on how you redeem your points.
A poor redemption can make airline miles look almost worthless. A good redemption, on the other hand, can completely change the economics of your credit card rewards.
I recently booked an Air India flight from Delhi to Varanasi, and the numbers were surprisingly good.
The Cash Fare Was Around ₹8,467
The flight I wanted to book was selling for approximately:
Cash Fare: ₹8,467
Instead of paying the entire amount in cash, I checked the award availability through Air India Maharaja Club.
The same flight was available for:
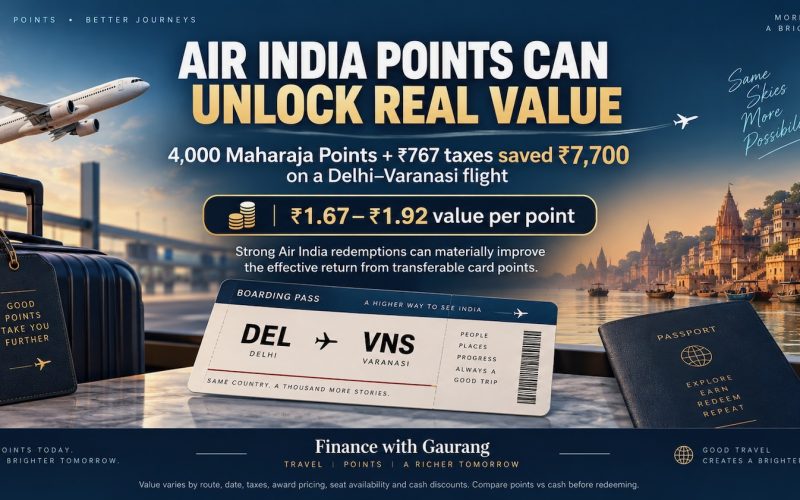
4,000 Maharaja Points + ₹767 in taxes and fees
That meant I was effectively using 4,000 points to avoid paying ₹7,700 in cash.
The Calculation
Cash Fare: ₹8,467
Less Taxes and Fees Paid: ₹767
Net Cash Saved: ₹7,700
Points Used: 4,000
So the value I received was:
₹7,700 ÷ 4,000 = approximately ₹1.92 per Maharaja Point
That is an excellent redemption value.
But There Is Another Way to Look at It
Whenever we calculate the value of airline points, we should not blindly compare them with the full published cash fare.
The more realistic comparison is against the fare we could actually have paid after using available discounts.
In this case, MakeMyTrip was offering a discount through HSBC TravelOne.
If we consider a 12% discount on the ₹8,467 fare, the effective cash price would have been approximately:
₹7,451
After subtracting the ₹767 taxes that were still payable on the award ticket, the effective cash saving becomes:
₹6,684
Now divide that by the 4,000 points used:
₹6,684 ÷ 4,000 = approximately ₹1.67 per point
So depending on how you calculate it, this redemption delivered roughly:
₹1.67 to ₹1.92 per Air India Maharaja Point
That is still a very strong outcome.
Why ₹1.67–₹1.92 Per Point Matters
This is where transferable credit card points become interesting.
Suppose your credit card effectively gives you a return of around 3% based on how you normally value its reward points.
If those points can be transferred to Air India and you are then able to redeem them at significantly more than ₹1 per point, your effective return can increase substantially.
A point that looks ordinary while sitting in your credit card account can become far more valuable once it reaches an airline loyalty program.
That is the real appeal of transferable reward points.
You are not simply earning points.
You are creating optionality.
Air India Maharaja Points Can Sometimes Deliver ₹1–₹2.5+ Per Point
There is no fixed value for an Air India Maharaja Point.
That is extremely important to understand.
On some redemptions, the value may be mediocre. On others, particularly where cash fares are expensive but award pricing remains reasonable, the value can become much more attractive.
Depending on the route, date, cash fare, award availability and taxes, it may be possible to extract roughly ₹1 to ₹2.5 or more per point.
But this should never be treated as a guaranteed valuation.
The right approach is to calculate the value every single time before transferring or redeeming points.
This Is Where Credit Card Transfer Partners Become Powerful
Several credit cards allow points or miles to be transferred to airline loyalty programs.
That means the reward currency you earn from everyday spends may eventually be converted into airline miles.
This can materially improve the effective return from your card if you redeem well.
Take a simple example.
If you transfer 5,000 credit card points to Air India in a 1:1 ratio, you would receive:
5,000 Maharaja Points
If you later manage to redeem those points at around ₹1.7 per point, the potential travel value becomes approximately:
5,000 × ₹1.7 = ₹8,500
That is where annual-fee cards can sometimes become much easier to justify.
You should not evaluate a card only by looking at its annual fee.
The more relevant question is:
What value am I actually able to extract from the card?
Axis Horizon Is a Good Example of How This Can Work
Consider a credit card that offers a welcome benefit of 5,000 transferable miles or points after meeting the required conditions.
If those points can be transferred to Air India at a 1:1 ratio, they effectively become:
5,000 Maharaja Points
At a redemption value of around ₹1.7 per point, those 5,000 points could potentially represent around:
₹8,500 worth of travel value
If the annual fee paid for the card is significantly lower than the value you are eventually able to extract, the economics start looking very different.
Of course, that value exists only if:
- the transfer ratio remains favourable,
- award seats are actually available,
- you genuinely need the flight,
- and the cash fare is high enough to make the redemption worthwhile.
This is why calculating value matters far more than simply collecting points.
Cashback Is Simple. Points Have More Upside.
Cashback cards are popular for a reason.
They are simple.
You spend ₹100, you get a defined percentage back.
There is very little thinking involved.
But the simplicity often comes with limitations.
Many high-cashback cards have:
- monthly cashback caps,
- category restrictions,
- merchant exclusions,
- lower earning beyond certain spends,
- and limited upside once the monthly cap is reached.
That does not make cashback cards bad.
They can be excellent for people with moderate annual spends who want simple, predictable returns.
But once your spending increases, or if you are genuinely interested in travel, transferable points can become far more interesting.
This Is the Difference Between Cashback and Miles
With cashback, the value is usually fixed.
₹1 cashback is worth ₹1.
With airline miles, the value is variable.
A point may be worth ₹0.70 in one redemption, ₹1.50 in another and potentially ₹2 or more in a particularly strong redemption.
That variability is both the advantage and the risk.
You need to know when to redeem.
This is somewhat similar to programs such as Accor, where people often value the loyalty currency highly because it can translate into strong real-world travel value.
Airline points work differently because their value is not fixed, but a well-timed redemption can create a comparable sense of outsized value.
Could Your Credit Card ROI Actually Double?
Potentially, yes—but only under the right circumstances.
Imagine your credit card gives you reward points that you normally value at around 3%.
If you transfer those points into a frequent-flyer program and manage to obtain nearly twice the value from each point, your effective return can rise sharply.
A theoretical 3% base return may start looking closer to 5% or more depending on:
- the card’s earning rate,
- the transfer ratio,
- the redemption value,
- and the taxes you have to pay.
This is why I would not judge a rewards card simply by the number of points printed in the marketing material.
The real question is:
What can those points become?
Always Calculate Before You Transfer
One mistake people make is transferring credit card points to an airline just because a transfer option exists.
That is not necessarily a good strategy.
Once points are transferred, they generally cannot be moved back to the credit card rewards program.
So before transferring, compare:
Cash fare you would realistically pay
minus award-ticket taxes and fees
divided by the number of points required
And do not forget opportunity cost.
If a ₹10,000 flight is available to you for ₹8,000 after a credit card discount, you should compare your award redemption against ₹8,000—not ₹10,000.
That gives you a much more honest valuation.
My Delhi–Varanasi Redemption
Coming back to my own booking:
Cash Fare: ₹8,467
Award Price: 4,000 Maharaja Points + ₹767
Net Cash Saved: ₹7,700
Value Per Point: ₹1.92
After considering the available cash discount:
Discounted Cash Fare: ₹7,451
Less Taxes Paid: ₹767
Effective Saving: ₹6,684
Value Per Point: approximately ₹1.67
For me, that was still a redemption worth making.
I was able to book the flight I needed while preserving several thousand rupees in cash.
And that, ultimately, is why airline points can be so useful.
Final Thoughts
The debate should not really be about whether Air India Maharaja Points are “good” or “bad.”
The better question is:
What value are you getting from them on the redemption in front of you?
At ₹0.80 per point, I may prefer to pay cash.
At ₹1.5 per point, the redemption starts becoming interesting.
At ₹1.7–₹1.9 per point, as in this example, the economics can be compelling.
And if you occasionally find redemptions delivering ₹2 or more per point, transferable credit card rewards start showing their true potential.
Cashback is predictable.
Miles require more work.
But when you understand how to earn, transfer and redeem them intelligently, those points can do something cashback usually cannot:
They can turn an expensive flight into a surprisingly affordable one.
Finance with Gaurang
Disclaimer: Reward-point values are not fixed. Redemption value varies based on cash fares, route, travel date, award availability, taxes and fees, transfer ratios and promotional discounts. Always compare the actual cash price available to you before transferring or redeeming points.
